By clicking a retailer link you consent to third-party cookies that track your onward journey. This enables W? to receive an affiliate commission if you make a purchase, which supports our mission to be the UK's consumer champion.
Aviva home insurance review
Aviva offers top-notch buildings cover and good customer scores
Aviva offers three home insurance policies – Signature, Online and Premium – and we've reviewed them all. It sells its Signature policy directly and the others via comparison websites.
We've also surveyed 540 Aviva customers who have recently made a home insurance claim.
Its home insurance is underwritten by Aviva Insurance Limited.
Please note that this article is for information purposes only and doesn't constitute advice. Please refer to the insurer's T&Cs before committing to any financial products.
Does Aviva offer the best home insurance?
Aviva
Each of Aviva’s policies has Best Buy buildings cover, and claimants rate its service.
Which? earns commission to fund its not-for-profit mission if you buy a product
‘Aviva could have had even more Best Buys’
Dean Sobers, Which? home insurance expert, says:
Aviva’s standard policy – called Signature – was among the top 10 we rated for buildings cover, scoring 75%. Its contents cover did even better, earning 77% and ranking sixth in our table. Signature is a Best Buy for buildings cover. If it were just down to the policy score, its contents cover would have made the cut, too. However, its lower-than-average acceptance rates for contents claims meant it missed out.
It offers a generous £3,000 cover for cash kept in the home, and has a comparatively high limit of £100,000 for alternative accommodation under its buildings cover. This is the total amount available for rental costs if your home is uninhabitable during the claim and you need to live elsewhere.
However, the cover isn’t perfect across the board. For example, its contents cover doesn’t include digital downloads, which most policies now do. It also has a fairly steep excess for escape of water (water damage caused by broken plumbing) at £450.
No-claims discount protection
If you have car insurance, no-claims discounts will be familiar to you – and with them no-claims discount protection (NCDP). Put simply, NCDP is an add-on that reduces the effect of making claims on your renewal premium.
NCDP is much rarer in home insurance – Aviva and Quote Me Happy (which it owns) are the only providers we reviewed that offer it. Aviva’s add-on shields your discount for up to two claims over a three-year period.
Premium and Online
While Signature is only available directly from Aviva, you can get Online and Premium cover through comparison websites.
Premium is the more comprehensive of the two. With 76% for buildings and 69% for contents cover, it’s a buildings Best Buy.
Online was slightly less impressive but is still a Best Buy for buildings cover, with a score of 73%. Its contents cover was in the bottom half of our table with 65%.
How did customers rate Aviva home insurance?
We asked Aviva customers who have recently made a claim how they felt about their home insurance.
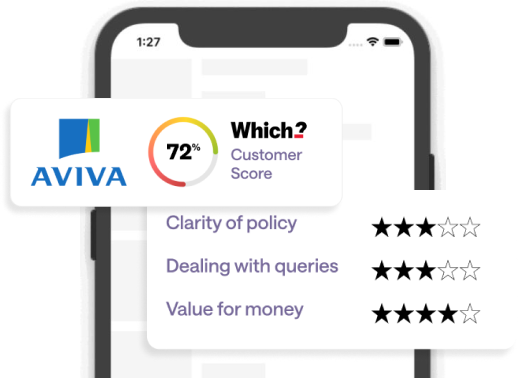
Aviva received a customer score of 80%. In our table of 21 providers, this put it in joint fourth place, along with two other insurance brands.
Customers also rated their most recent claim. Here, Aviva received a score of 81% – placing it joint third of the 22 providers we rated. See the list of results here.
What Aviva home insurance customers said
When we asked more about the rating customers gave Aviva, one claimant told us: 'I have only ever had good experiences with them,' while another commented that a claim with Aviva was 'handled quickly and in a positive manner'.
One satisfied customer said: 'My claim was assessed judiciously and swiftly.'
Customer satisfaction
How comprehensive the policies are
★★★★☆
How affordable the policies are
★★★☆☆
Clarity of policy
★★★★★
Dealing with queries
★★★★☆
Dealing with complaints
★★★★☆
Value for money
★★★★☆
Fair treatment of long-standing customers
★★★★☆
Table last updated in September 2026. Next update in September 2027.
Aviva's Signature policy is only available direct. Its Online and Premium policies are available on these price comparison websites:
Compare the Market
Confused.com
Go.Compare
MoneySuperMarket
Want to pay monthly? Aviva charges variable interest on its home insurance policies, so you might be better off paying annually on an interest-free credit card.
The above information is correct as of August 2026. For more ways to save money when buying insurance, see our guide to cheap home insurance.
Visit Aviva directly to find out more about its home insurance policy.
How does Aviva compare with other providers?
With a customer score of 80%, Aviva sits in fourth place overall in our satisfaction table, coming just below Tesco (81%) and slightly ahead of 1st Central, HSBC, Lloyds Bank and Nationwide (which all scored 79%).
Its standard Signature buildings policy (available direct through its website) scored 75% and ranks joint second in our standard buildings cover table, along with the standard policy from NFU Mutual.
For contents insurance, Aviva's Signature policy scored 77% and sits in first place among standard policies. This positions it slightly ahead of NFU Mutual (76%).
Aviva home insurance: how can you claim?
The contact number to make a claim is 0345 030 6945.
If you need to contact Aviva about a home emergency cover claim, call 0345 300 3346.
You can also find out more about making claims online on the Aviva website.
If your priority is cover for your home itself, rather than the things in it, Aviva meets our Best Buy standards and is well worth considering if the price matches your budget.
However, our verdict on its contents cover isn't quite as glowing. Although Aviva is highly rated for customer satisfaction and its contents cover looks great on paper, it has lower-than-average claims acceptance rates for contents-only policies.
How we rate home insurance
To be a Which? Recommended Provider, an insurer must:
Be regulated by the Financial Conduct Authority (FCA)
Be available to the general public
Have received responses from 40 or more customers in our survey
Achieve high scores in our customer satisfaction survey
Achieve an average or higher policy score
Achieve an average or higher claims satisfaction score
Policy analysis
We analyse and rate 177 aspects of cover across insurers' policies, including their key buildings and contents features, and elements applicable to both kinds of cover (such as admin fees). We use this data to award each provider policy scores for its buildings and contents cover.
Initially, we score all of the product elements out of five, reflecting how competitive each policy is in this area compared with other insurance products. We also assess how important different policy elements are to consumers when choosing and using their home insurance, and factor this in when calculating our policy scores. More important features (such as alternative accommodation cover) will have more of an effect on the score than some other features (such as cover for the contents of your freezer).
Customer survey
We also surveyed 3,419 members of the public who had made a claim in the past two years. The survey was conducted in May-June 2026.
Our customer score reflects the general satisfaction of customers with their current insurer and their likelihood of recommending it. The claims score reflects how satisfied they were with how their most recent claim was handled and their likelihood of recommending the insurer for claims.
We review a lot of policies – and being a Best Buy recognises the individual products that stood out as being the most comprehensive in our analysis. It doesn't reflect customer service. However, we won't give a provider a Best Buy where there's evidence – from our surveys or from Financial Conduct Authority data – of poor service or a poorer-than-average record of paying claims.
Buildings Best Buy policies must have a minimum buildings policy score of 73%
Contents Best Buy policies must have a contents score of at least 70%
Additionally, we look at how consistently good the cover is in policies. To make the cut, a policy needs to have scored at least three out of five points in two thirds of the areas we've rated (find out more: how we rate policies).
Lastly, all Best Buy policies must have – or make available – the following levels of cover as a minimum:
Buildings
Flood, storm, subsidence and accidental damage cover; Cover for burst or blocked pipes; Trace and access cover (£5,000); Alternative accommodation (£50,000) with no time limit; Property owner liability (£1m); Replacement of locks or keys for external doors (£500); Home Emergency Cover (£500 and includes the central heating system).
Contents
Accidental damage cover; Theft and damage of contents in the open; Theft and damage of contents from outbuildings; Business equipment; Alternative accommodation (£15,000); Money in the home (£500); Valuables (unspecified single item limit – £2,000); Personal possessions (unspecified single item limit - £1,000); Replacement of locks or keys for external doors (£500).
We’re not influenced by third parties. We work entirely on behalf of you, the consumer – nobody else. See our statement of editorial independence for more.