
Need home insurance?
Use our customer scores to help you choose a great deal at MoneySuperMarket
Compare dealsWhich? earns commission to fund its not-for-profit mission if you buy a product
By clicking a retailer link you consent to third-party cookies that track your onward journey. This enables W? to receive an affiliate commission if you make a purchase, which supports our mission to be the UK's consumer champion.

Dean is an award-winning personal finance writer who’s spent over 15 years helping consumers navigate the tangled and fascinating world of insurance.

We've partnered with MoneySuperMarket to help you compare a wide range of home insurance options in one place, with added insight from Which?
Get a quote with MoneySuperMarket and we'll highlight Which? Best Buys and Recommended Providers in your results.
This is a Which? exclusive, so you won't find our scores or expert analysis on other comparison sites.
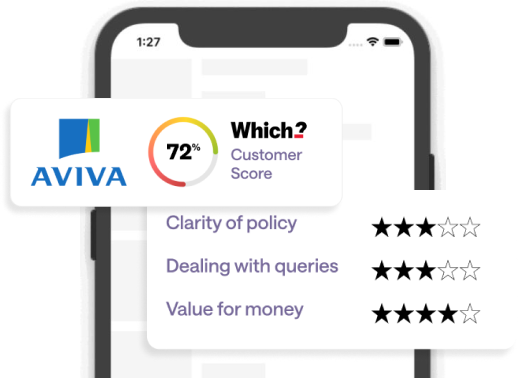
We rated 177 elements of each policy, covering buildings, contents and admin points such as fees.
We asked 3,419 home insurance customers who made a claim within the past two years to score their insurer.
In this article
Home insurance premiums rose steeply in 2023 and 2024, then fell towards the end of last year – but they're showing signs of going up again.
Between April and June 2026, the average cost of a combined home insurance policy stood at £383, according to the Association of British Insurers (ABI). This is lower than the average cost at the same time last year, but £8 higher than between January and March.
What you'll pay depends on:
While you can't easily change some of these things, there are simple tips you can follow to minimise the amount you need to pay, without compromising on cover.
Use our customer scores to help you choose a great deal at MoneySuperMarket
Compare dealsWhich? earns commission to fund its not-for-profit mission if you buy a product
Your current insurer will send you a renewal notice about a month before your policy is due, outlining the full details of your new policy and premium.
Getting quotes from other providers around this time allows you to shop around and haggle. Also, getting quotes 10 or more days before your current policy ends could save you money compared with waiting until closer to the renewal date.
According to data from MoneySuperMarket, average annual home insurance premiums cost £294 for those who wait until their current policy ends to renew, compared with £278 for those who buy 10 days in advance. It's not a huge saving, but every little counts.
| Days before policy renewal date | Average annual premium |
|---|---|
| Day insurance ends | £294 |
| 1 | £289 |
| 10 | £278 |
| 20 | £277 |
| 30 | £279 |
Source: MoneySuperMarket. *Based on the median annual price for home insurance policies sold through MoneySuperMarket between February 2026 and April 2026.
Some home insurance providers automatically take a deposit ahead of renewal in an attempt to secure your business for another year.
The payment, usually one month's premium, only applies to pay-monthly customers and is taken from your account a month before renewal. The amount is deducted from next year's premium if you decide to stay on.
If you know your home insurance policy is coming up for renewal, check whether your provider levies pre-renewal deposits to avoid being caught off guard.
While everyone should seriously consider contents insurance, buildings insurance is only a necessity if you're responsible for the condition of the property itself.
Many policyholders could be over or underpaying for their home insurance by incorrectly calculating the value of their building and contents.
When setting the building value, you need to use the rebuild value (the cost of rebuilding the property from scratch), not the market value (what it would cost to buy the property if it were for sale).
Market value is often higher than rebuild value. However, rising prices in construction materials and labour costs may have driven up the true rebuild value of your property since you initially took out your insurance. For both these reasons, it's worth reviewing your home's rebuild price when you renew your policy.
To estimate your building's rebuild value, use the Association of British Insurers' calculator or a commissioned survey valuation.
Meanwhile, be careful not to underinsure your contents in an attempt to get cheap insurance. Consider all the items you have and what it might cost to replace them with new equivalent goods.
Also, think hard before setting a high excess (the amount you have to pay in a claim). This will reduce your premium, but could make it pointless to claim in some situations.
Different comparison sites have slightly different insurers and policies available – and prices can differ. That's why it makes sense to run quotes on several comparison sites.
The main price comparison sites for insurance are:
The first time you run quotes on these sites may involve some form-filling, but they save your details, so next year you'll just need to do a quick review.
Use comparison sites alongside our home insurance policy scores, to check that cheap policies have the cover you need.
Don't worry about your credit rating being affected, as the quoting process only involves 'soft searches' that aren't visible to other companies. A visible 'hard search' is only conducted when you apply for policies with monthly payments.
Cashback websites, including Quidco and TopCashback, pay a cash reward when you click through them to buy goods or financial products. They can link to insurers' websites, but also to comparison sites.
Just make sure the policies aren't costing more through cashback sites than they would otherwise. A £400 policy with £100 cashback is far from a bargain if you could get the same cover elsewhere for £250.
Comparison sites are a great time-saver, but they're not the whole story.
Which? Recommended Provider NFU Mutual isn't on comparison sites, and neither are some of our Best Buy policies from Aviva, Ecclesiastical and Sagic.
It could be worth getting quotes from these providers' websites as well as comparison sites.
Before you pay extra for add-ons, take a critical look at whether you really need the additional cover.
You could have spent years paying for a laptop to be covered outside the home, for instance, without ever taking it out. Or for home emergency cover when you have modern plumbing and an extensive service plan from a utility company.
You may also have opted for bicycle cover a few years ago when taking out the policy, but rarely use the bike.
Finally, when checking a quote, watch out for 'endorsements'.
In insurance, 'endorsement' is a term somewhat confusingly used to describe an alteration made to a customer's terms or cover to reflect their specific case. It should be listed in the policy schedule document.
For example, if you live in a property that was flooded in the past few years, your insurer might add an endorsement excluding flood cover from your policy.
Find out more: do you need home insurance add-ons?
Paying monthly is essentially taking a loan, usually at high interest, from your provider. APR varies, but it can be as much as 30%.
Always check pay-monthly fees and compare the cost against annual cover. You can see which insurers offer monthly payments at no extra cost in our guide to insurers' fees and charges.
You could spread the cost of an annual premium over 12 months or more by using a 0% purchase credit card.
If you're determined to stay with your current provider, you can use cheap home insurance deals elsewhere as leverage when haggling.
You can boost your chances of being offered a cheap home insurance deal by following our tried-and-tested haggling script.
In the long term, improving your home security could help.
Most insurers require a minimum level of security before they accept you as a customer, such as deadlocks on external doors and locks on accessible windows. But going beyond that can get you cheaper quotes:
If your property is heritage listed, has a thatched roof or other unusual feature, you may find you get fewer home insurance quotes or that the quotes are prohibitively expensive.
An insurance broker may be able to find specialist insurers and save you money.
Use the 'find insurance' service offered by the British Insurance Brokers' Association, or call 0370 950 1790.
Which? Money members can also contact the Which? Money helpline for advice on finding cover.
If you rent, you'll only need contents insurance: your landlord should handle the buildings insurance.
While there are specialist short-term insurance policies available and policies covering a single room, we advise being sceptical.
Always compare the premiums and cover levels from renters' policies with what you could get from more 'traditional' contents cover.
If you're in a house share, all inhabitants will need to be named on the contents policy. It's important to keep the details accurate and up to date, or you risk the insurer turning down any claims you make.
Find the right policy for your home using the service provided by MoneySuperMarket
Get a quote now